


Every single business in the world is bound together by one simple fact. To succeed, they have to grow. This means in order to make the most out of their enterprise, they have to make sure they are constantly pushing towards upward growth and development as a company. To do this, they must develop a global expansion strategy at one point or another. Trading on the global marketplace is widely considered to be the pinnacle of success for any company.
However, going global is a very long, complicated process that can go horribly wrong if you don’t exercise appropriate caution and research what you must do beforehand. We are going to take a look at the different things that you need to consider when it comes to going global as a company here and now.
📖 Key takeaways
- Expanding internationally means no walking in the park. Despite the myriad of benefits that come with “going global,” there are still a lot of firms that haven’t jumped abroad. After all, it’s a massive endeavor requiring time, effort, research, and patience.
- To successfully expand your business worldwide, having a smart global strategy is crucial. Help your team understand what it takes to expand globally by checking out the global expansion process and strategies.
Understanding Global Expansion
Global expansion is a business growth strategy that extends a company’s operations into new foreign markets. So, it is the process of expanding your company’s operations from one market to a foreign market, offering benefits like cost reduction, risk mitigation, and increased revenue.
The allure of global expansion lies in its potential to significantly boost revenue, increase market share, and enhance brand recognition. However, it also comes with its own set of challenges, such as navigating cultural and language differences, adapting to local market conditions, and ensuring compliance with various regulatory requirements. An international strategy can help maintain consistent branding and product features across different regions.
International expansion strategy involves conducting research, careful planning, ensuring regulatory compliance, and adapting your brand image to new cultures.
Global expansion refers to the process of extending a company’s operations into new international markets. This involves more than just exporting products; it includes establishing a presence in foreign countries and adapting to the unique conditions of each local market.
Companies can achieve global growth through various strategies, such as exporting, licensing, franchising, or setting up wholly-owned subsidiaries. Each method or strategy has its own advantages and challenges, and the choice of strategy should align with the company’s overall goals and resources.
How to Develop a Global Expansion Strategy?
A global expansion strategy is a formal business plan outlining how a company intends to expand into foreign countries and markets. At the end, this document should include clear timelines and budgets, thorough research, realistic goals, and dedicated talent.
Creating a robust global expansion strategy is essential for companies looking to expand internationally. A well-crafted strategy helps navigate the complexities of global expansion and ensures that the company’s goals are met.
Simply put, you must develop a comprehensive plan that guides the company’s international growth and helps it achieve success in new markets.
1. Conduct Market Research
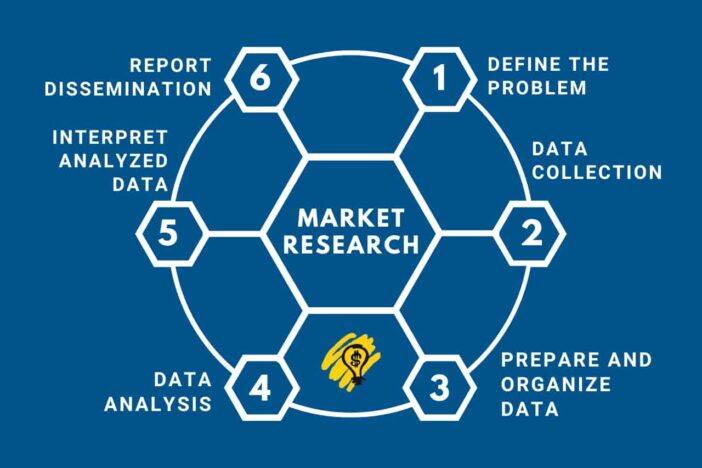
Market research is a cornerstone of any effective international expansion strategy. It involves collecting and analyzing data about the target markets and potential customers to understand their size, growth potential, competitive landscape, and consumer behavior.
This information is crucial for identifying opportunities and challenges in the new market. Such research can help you choose and adjust appropriate approaches to meet the specific needs and preferences of the foreign market, thereby increasing your chances of success. In such a way, you can make informed decisions and develop strategies that align with their international expansion goals.

You can follow our market research methods guide and sources of information for conducting market research.
Related: How To Reach Your Target Audience and Sell Your Product
2. Set Global Expansion Goals

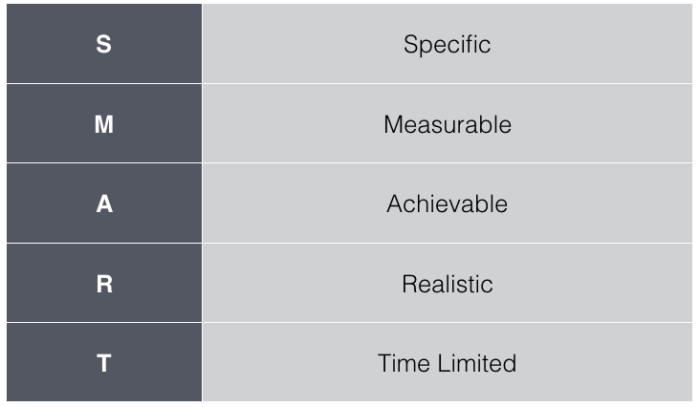
You can’t hit the ground running if you still haven’t defined your goals. Try to segment the process into short- and long-term strategies. Through this method, you can set small yet realistic goals for each stage and easily keep track of the changes at every level.
Take note: your goals should be timely, relevant, specific, and measurable. Schedule dates, use numbers, and be as specific as you can.
3. Create a Market Entry Strategy
A market entry strategy is a detailed plan for entering a new international market. It outlines the most effective approach for establishing a presence in the target market, whether through exporting, licensing, franchising, or setting up a wholly-owned subsidiary. The choice of entry strategy should be based on comprehensive market research and should consider the company’s objectives, resources, and capabilities. A well-defined entry strategy helps companies navigate the complexities of international expansion and ensures that they are well-prepared to meet the demands of the new market.
Selecting the right entry approach is critical for companies expanding internationally. An international strategy can be particularly effective in maintaining consistent branding and product features across different regions, appealing to consumers based on the established brand reputation.
The decision should be based on a thorough analysis of the target market, including market size, growth potential, competition, and consumer behavior. Whether it’s exporting, licensing, franchising, or establishing a wholly-owned subsidiary, the chosen strategy should align with the company’s overall international expansion objectives.
4. Analyse Country-Specific Factors Impacting International Expansion Strategies
Even though the previous steps are important, they are still not enough to develop a global expansion strategy. You must consider some additional country-specific factors that will help you prepare better for international expansion.
Let’s look at some of them:
Import and Export Tax, Currency and Rising Prices in Global Expansion Strategies
For a business going global, money can be a difficult subject.
Proper tax and finance systems should be set up ahead of time. By doing so, you can be sure that you are receiving reporting earlier and that your foreign entity is following local corporate policies.
You also need to establish relationships with local banks, develop a transfer pricing study, work out proper risk management and cash repatriation plans, and report sales and VAT.
There are things you must consider when it comes to expanding your business onto the world stage. For example, the currency is different in every part of the world. What you pay for in one currency in one part of the world, someone else pays for in another. Obviously, this leads to confusion and exchange rates unless you have a consistently sensible set of prices.
In this instance, what we are suggesting is that you take the time to adjust your prices to account for import tax, export tax, the conversion rates of different currencies, and any other hidden costs that may arise during the process. Port services and mail forwarding are also things to consider because any business operating on a global scale will have communications from customers all over the world.
Trading Laws in International Markets
A consistent issue that a lot of businesses have is that when it comes to trading their products on the global marketplace, they forget to take into consideration the laws and regulations that govern each country. Some laws ban certain products, whereas others will impose age limits on them.
As a direct result of this, you need to make sure that you are obeying all the different laws and regulations that govern every part of the world and that you respect every country’s right to police their citizens how they choose.
Some countries are famous for being highly regulated and litigious. If you are stepping into any such region, ensure all legal processes are implemented. It will minimize the commercial risks and ensure you don’t face any trouble settling.
Keep an eye on government requirements regarding documentation. Usually, setting up a business in a new region requires a lot of paperwork. Therefore, create localized commercial agreements. In addition, go through all the industry-specific regulations to ensure compliance with the law. You also have to maintain corporate records and governance to avoid legal complexities.
Consider Multiple Languages for International Expansion
So, one of the first and most fundamental lessons that you need to take into consideration is that the English language is incredibly common around the world, but it’s not the only way to speak. Many people communicate in languages you probably haven’t heard of before, and to drive up your sales and maximize profit, you need to be able to speak to and communicate with them effectively.
For the successful entrepreneur, this may include hiring someone who is fluent in another language so you can deal with multiple forms of communication. In some cases, it may even involve paying for translation programs so that you can speak directly to your customers, and they can talk to you without having to hire multiple staff. Whatever you do, you have to be ready to trade on a global marketplace and thus accept that the language will change.
Understand Local Culture in the New Market
Any idea what is the local culture like in the region you are expanding? We may not realize, but there are substantial cultural differences. That means you have to understand the new market and become familiar with local customs and working practices. And the best way to do this is by spending time in the market. You can attend trade shows and webinars to see how things happen in the target country.
Likewise, you can design surveys specifically for local audiences to determine their preferences. You can ask about their product choices, favorable communication channels, and shopping styles. It will allow you to conform to the distinctive demands of a particular geographic region.
5. Check Your Organizational Preparedness for Global Growth
Your firm should take cultural aspects such as language, customs, or regulations into consideration at all times. Your entire team has to abide by the procedures and policies implemented in the area of your business to make sure that all employees are on the same page.
Everyone needs to work toward one goal, and that is to execute the company’s plans. Having a “one size fits all” mentality will not do your company any good and may lead to negative effects down the road.
Also, certain countries are notorious for being very litigious. This is why it’s important for your business to establish strong legal processes to avoid unnecessary commercial risks down the line. Keep in mind that government agencies also have strict policies that require legal documentation to be submitted before operating a business in the country.
Build Your Beachhead Team
Most companies attempt to open with executives from the mother company or just quickly build a local team. This is not an ideal approach for firms that are expanding globally because it takes a lot of time, puts your company at a higher risk of failing, and cuts your marketing time.
Instead, you need to tap a team of senior interim executives who could help get things started. They can help you drive certain initiatives while the company finds the ideal senior management team.
While it is essential to have experienced experts on board, you also need local expertise. Most companies step into the target market with executives from the parent company. Therefore, look for experts who can drive initiatives and validate assumptions.
Besides years of experience, find candidates with advanced qualifications. Having a team with the know-how of global management will go a long way in running a business effectively.
Moreover, the option of outsourcing should be kept on the cards. If marketing and financial management seem like a struggle, feel free to outsource them to local service providers. They will have extensive knowledge of accounting laws and marketing dynamics, helping you establish a name in the new region.
Adjust Your Product Strategy According to New Markets

Last but not least, make sure that the product you’re planning to offer is going to be market-worthy. Come up with a product or service that will appeal to any foreign market. Carry out necessary tests for your product in your target market and see if any adjustments are needed.
Since you already have a facility overseas, you can use those to help you make decisions on how you should adjust your product in conjunction with the new market. As things progress, identifying new and much better opportunities will be a breeze.
How to Establish International Partnerships?
One of the most important things you must do in order to ensure that your global strategy will succeed is to build strong international partnerships.
1. Build Relationships with Local Experts
You must first build relationships with trusted local experts in your target markets to successfully establish international partnerships and achieve international growth. These experts possess invaluable knowledge of the local business landscape, cultural nuances, and regulatory environment.
If you build strong collaboration with them, you can gain insights that will help you successfully manage potential challenges and seize opportunities.
For example, if you’re expanding into the Japanese market, partnering with a local consultant who understands Japanese business etiquette and consumer behavior can provide you with a competitive edge.
2. Connect with Legal and HR Professionals
Connecting with legal experts and HR professionals is another crucial step in forming international partnerships.
Legal experts can help you understand and comply with the complex regulations of specific markets, ensuring that your business operations remain lawful and efficient.
Meanwhile, HR partners can assist in recruiting and managing global talent, which is essential for establishing a presence in a new market.
For example, if you’re entering the European market, collaborating with a local HR firm can help you manage the complexities of labor laws and international talent employment practices specific to each country.
3. Partner with Benefits Brokers and Payroll Providers
Partnerships with benefits brokers are vital for managing your global workforce effectively because they can help you design competitive compensation packages that attract and retain top talent.
Additionally, payroll providers ensure your employees are paid accurately and on time, sticking to local tax and labor laws.
For example, if you’re expanding into Brazil, a local payroll provider can help you manage the country’s complex tax system and ensure compliance with local regulations.
4. Manage Cultural Differences and Ensuring Compliance
International partnerships can also assist in managing cultural differences and ensuring regulatory compliance. By working closely with local people, you can adapt your business practices to align with cultural expectations. This cultural alignment fosters trust and strengthens your relationships with local stakeholders.
Moreover, local partners can help you stay updated on regulatory changes, minimizing the risk of non-compliance. For example, in the Middle East, understanding cultural norms and legal requirements is crucial for successful business operations, and local partners can provide the necessary guidance.
Global Expansion Best Practices and Common Mistakes
Learn from Others
Learning from others who have expanded globally can make a big difference to your success in new markets.
Here are some key points from businesses that have expanded globally:
- Do Market Research: Know your target audience.
- Have a Global Expansion Strategy: Define your goals, target markets (if you’re expanding into multiple markets), and entry strategy. A clear global expansion strategy ensures everyone is aligned and focused on the same objectives.
- Choose the Right Entry Strategy: Select entry strategies that match your business goals and the international market you’re entering. Whether it’s exporting, licensing, franchising, or setting up a local subsidiary, the chosen strategy should support your overall global expansion plans.
- Build a Local Team: Hiring local talent who knows the market, culture, and language can be a big plus. A local team helps you build relationships with customers and partners.
- Adapt to International Market: Be prepared to adapt your products, services, and business model to the specific needs of the international market you’re targeting. Flexibility and responsiveness to local preferences can be a big competitive advantage.
Common Mistakes
While global expansion offers huge growth opportunities, it also has pitfalls. Here are some common mistakes businesses make and how to avoid them:
- Not Enough Market Research: Skipping market research can mean you don’t understand your global target market, its size, growth potential, and competition. So, always invest time and resources in researching global markets.
- Bad Market Entry Strategy: Choosing the wrong entry strategy can mean failure. For example, exporting might not be right for a business that needs a local presence. Assess your goals and resources carefully to choose the right strategy.
- Local Support: Failing to build a local team or provide enough local support can limit your ability to succeed in a global market and build relationships. Make sure you have the right local expertise and support in place.
- Unable to Adapt: Not adapting to specific global market conditions can make you uncompetitive. Be flexible and willing to change your products, services, and business model to match local preferences and demands.
- Risk Management: Not managing the risks of global expansion, such as currency fluctuations, regulatory changes, and cultural differences, can lead to big financial losses. Develop risk management strategies to mitigate these risks.
Conclusion
Let’s be real here – you’re still at the starting line of the race. And we mean that in a good way. If you’re feeling pressured by all the planning and preparations required to expand globally, don’t fret – you’re not alone. Remember, you can overcome any hurdle by setting small, realistic goals and making plans that get you closer to meeting them. Global expansion is a great opportunity to help your business grow as long as you take one step at a time.
Trading in a global marketplace is very rewarding. However, at the same time, it does require you to be sensible about how you do things. There are a lot of different considerations that you’re going to want to think about because they will influence exactly how successful your business is on the world stage. It’s not just a case of announcing that you trade globally and expecting profits to suddenly drive up because unless you’ve taken adequate steps to prepare, you will flounder.


