What if I told you there was a way to improve inventory management for your small business? Or can you make your inventory management system more efficient and less time-consuming? What if there is a way to increase your revenue while decreasing the amount of time that it takes to manage your inventory? Then what would you think?
Small business owners are often plagued with the dilemma of how to best manage inventory and costs. This is where most small businesses make mistakes. These mistakes cost money, cause frustration, and can even put your business out of business. The key to efficient inventory management is knowing how much inventory to carry at all times.
Let’s start at the beginning of your journey to improve inventory management in your company.
📖 Key takeaways
- Do you know inventories can cover 20% to 60% of your company’s total assets on the balance sheet? So, you really need to think about how to achieve good inventory management in your small business.
- A company with strong inventory management will have the ability to forecast what it needs for the coming weeks and months, prepare to meet the demands of customers, and plan for when supplies will run low.
- If you implement a proper inventory management system inside your company, you will decrease your costs, and in such a way improve cash flow and profitability.
What is Inventory Management?
Inventory refers to the stock of a company’s products. These include all of its goods that are currently in the supply chain – both raw materials and finished goods – as well as those that have been purchased but aren’t yet in the supply chain.
If your company is a service-oriented company, you probably think that this is not something that matters to your company. But, if you analyze your company regarding different material flows, you can easily see that even if your company is a service company, you are still dealing with some types of inventories. All types of companies will always require papers, supplies, spare parts, and other similar things. They are not big rates on your balance sheet, but you can still make some improvements.
Inventory management is the process of planning, tracking stock levels, and the movement of goods and controlling the inventory in your company, from raw materials to the final products or services that will be in the hands of your customers.
This process consists of a set of activities that help organizations reduce inventory and increase the speed of delivery. It includes key steps such as receiving goods, inspecting, sorting, monitoring inventory levels, and triggering reorders, emphasizing the importance of understanding each step to minimize errors and optimize inventory management strategies.
When you’re running a physical store, you have to deal with the physical aspects of your inventory. This could include things like:
- How much space do you need to store items?
- How do you manage shelf space and display products?
- How many employees do you need to help manage your inventory?
- How often should you rotate your stock?
- How do you keep the optimal levels of inventory?
Types of Inventory

There are several types of inventory that you must manage, each serving a different purpose in the production and sales process. Let’s quickly look at them:
Raw materials
These are the basic materials used to produce goods that have not entered into the production process.
For example, a furniture manufacturer would consider wood, nails, and varnish as raw materials. The restaurant onwer will have different type of raw food and beverages. So, different types of businesses will have different requirements for input materials.
Work-in-progress (WIP)
WIP or processing items are products that are in the process of being manufactured or assembled. So, these items are work-in-process items that are being worked on or waiting to be worked on.
For instance, a partially assembled piece of furniture would be classified as WIP.
Finished goods
Finished goods are the final finished products that are ready for sale. So, this inventory is the output from your production process that waits to be sold or distributed to your customers.
Examples include completed furniture pieces ready for display in a showroom.
Transportation inventory
Transportation inventory is the materials or goods that are in transit from one location to another. So, transportation inventory can be work-inprogress items moving between your processes and finished products that are currently inside your distribution system.
This type of inventory is necessary for businesses that require shipping their products to customers, such as online retailers.
Examples include shipping items from a manufacturer’s warehouse to a distribution center.
Safety stock inventory
Safety stock is a reserve inventory that ensures there are enough products on hand in case of unexpected spikes in demand or delays in production. It acts as a buffer to prevent shortages and keep operations running smoothly.
This type of inventory is especially important for businesses with seasonal fluctuations in demand or those operating in industries with long lead times for production.
Related: Safety Stock Inventory: Essential Tips and Calculations
Maintenance, repair, and operations (MRO) goods
These are the materials and equipment used to maintain and repair products. This category includes items like spare parts, tools, and cleaning supplies.
Understanding these different types of inventory helps businesses manage their stock more effectively and ensures that each category is adequately monitored and controlled.
Key Measures for Managing Inventory
A key measure of efficiency in inventory management is the impact of inventory on corporate profitability. Effective inventory management can improve profitability by reducing costs or by supporting increased sales.
In order to properly manage inventory, you should track and monitor several key measures:
1. Inventory Turnover Ratio

This measures how quickly your inventory is sold and replaced within a specific time period. A higher turnover ratio indicates more efficient management, while a lower ratio may indicate excess or overstocking.
You can calculate the inventory turnover rate when you divide COGS (Costs of Goods Sold) or annual sales by the average value of inventory. Usually, you will use COGS instead of sales because inventory is valued as a cost, while sales include your business’ markup.
You can calculate average inventory if you sum the inventory at the end of a period with the value of inventory at the end of the previous period and divide the sum by 2.
Related: Inventory Turnover Ratio: Increase Your Business Efficiency
2. Economic Order Quantity (EOQ)

The most economical order quantity is a measure that can help you determine the optimal quantity of inventory to order at one time, taking into account factors such as handling costs and ordering costs. It aims to balance the cost of holding too much or too little inventory.
As you know, we have costs for handling inventories and ordering costs that are fixed cost of placing orders. The sum of both costs is the total costs that we will have. You can calculate EOQ using following formula:

Related: How to Calculate Economic Order Quantity for Your Business
3. Stock-to-Sales Ratio
This ratio compares the amount of stock on hand (average inventory value) to the expected net sales for a given period. It helps you determine if you have enough inventory to meet demand or if you need to adjust your production or ordering levels.

Related: Stock to Sales Ratio: Easy Calculation & Management Tips
4. Carrying Cost of Inventory
This includes all the expenses associated with holding inventory and is usually presented as a percentage of the total inventory value, which can be from 20%-30%.
These costs include storage costs, warehousing employee salaries, stock insurance and taxes, transportation, handling, depreciation, shrinkage, and opportunity costs.
Related: Carrying Cost of Inventory
5. Safety Stock Inventory
This is extra inventory kept on hand as a buffer to protect against unexpected increases in demand or delays from suppliers.
Safety stock can help you minimize the impact of stockouts and maintain customer satisfaction from one side, but it will increase your costs.
Inventory Management Techniques
Inventory management techniques are methods used for the optimization of inventory levels, reducing costs, and improving efficiency. Some common inventory management techniques include:
Just-in-Time (JIT) Inventory Management
Just-in-time (JIT) inventory management is a technique or strategy that comes from lean manufacturing that requires ordering and receiving inventory just how much you need at the right time in order to meet customer demand.
This approach aims to minimize inventory levels and reduce waste by only producing and storing what is needed. JIT inventory management requires accurate demand forecasting and close relationships with suppliers to ensure that inventory is delivered on time.
Related: Mastering Just-in-Time Inventory Management
Kanban Inventory Management System
A kanban system utilizes visual signals, such as cards or bins, to signal when more materials should be ordered or produced. This system also comes from lean manufacturing and can help you to maintain optimal levels of inventory and avoid overstocking.
Related: Master the Kanban Inventory Management System for Optimal Efficiency
ABC Analysis

ABC analysis is a technique used to identify the most valuable products that contribute the most to your overall business profitability.
This technique classifies inventory into three categories: A, B, and C (as in the image above). “A” categories are high-value products that require tight control to avoid excess stock or shortages. B items have moderate value and need a medium level of control. C items are low-value products that can be managed with looser controls.
You can compare different product categories you have on stocks through income, demand, or profitability and put your focus on always having the most important product categories on stocks.
First-In-First-Out (FIFO) and Last-In-First-Out (LIFO)
FIFO is a method of inventory management where the oldest products are sold or used first. This ensures that perishable goods are not left to spoil and reduces the risk of holding onto excess inventory.
On the other side, the LIFO inventory management system requires the newest products to be sold or used first.
Vendor Managed Inventory (VMI)
In a VMI system, the supplier takes full responsibility for managing customer inventory levels. This allows for more efficient communication and coordination between the supplier and customer, reducing the risk of stockouts and overstocking.
Supply Chain Management
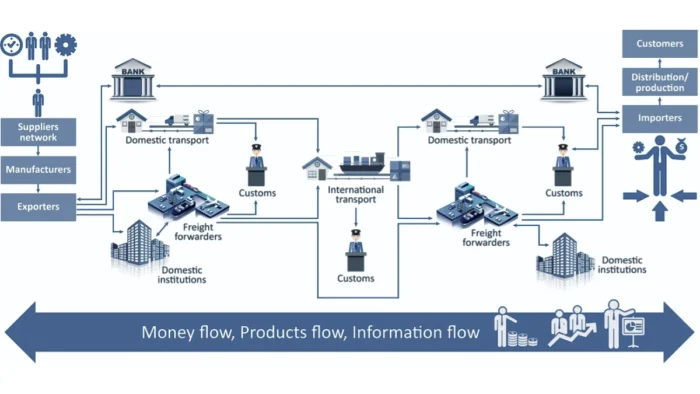
Supply chain management is a process of managing supply relationships outside a company and the flow of stock into and through a company. So, inventory management is essential for a properly running supply chain.
Related: How to Streamline Your Supply Chain Management Process for Optimal Efficiency
Periodic Inventory System
A periodic inventory is a method of tracking inventory where the quantity of items on hand is only checked at specific intervals, such as monthly or quarterly. This allows you to have a general idea of your stock levels without having to constantly track every single item.
Perpetual Inventory Management
This involves continuously tracking and updating the levels of inventory in real time with the help of technology such as barcodes and RFID tags.
With perpetual inventory management, you will ensure accurate inventory records and quickly respond to changes in demand.
Inventory Management Process
Storing inventory costs money. Business owners get upset with items gathering dust on shelves and staying in the store for a long time. Running out of stock means customers fail to get the products they need.
Finding a balance between stocking up products in demand and reducing slow-moving inventory with an effective inventory management plan is essential for business growth.
1. Determine Demand
Consumer demand determines the amount of inventory your business requires. Historical sales data will show consumers’ purchasing patterns. If you’re selling thirty-liter bottles of cooking oil per day, a good stock plan should meet the customer demand daily and reduce cases of high stock levels.
Business owners may keep select products in inventory despite low or irregular demand. Keeping products that are hard to acquire quickly is a good decision. Also, ordering products in a hurry costs more. Compare the costs of maintaining the goods and the profit margins to make informed decisions.
Demand forecasting is the process of predicting future demand for products or services. It involves analyzing historical sales data, market trends, and other factors to estimate future demand. Accurate forecasting is critical for businesses to ensure that they have the right amount of inventory on hand to meet customer demand.
2. Track Inventory

Stock management can only thrive when businesses can track their stock. For an inventory system to succeed, tracking mechanisms should be top-notch. Catalog your company’s stock and check changes on time. Point-of-sale software will help with tracking inventory.
Small businesses using ingredients to form an inventory base find tracking stocks hard, but it’s essential. You can document the ingredients that go into the finished cabinet or dish and deplete ingredients from the store after placing an order with a customer.
3. Replenishment Inventory Plan
We’ve seen that inventory planning and control rely on sound management of the supply chain. Factors to consider when planning for inventory replenishment include;
- The period between ordering and receiving an inventory
- The potential difficulties in ordering stock
- Possible reordering points
An effective inventory system works best, knowing that you’ll receive stock quickly.
For the products you regularly require, set a replenishment plan. The plan can range from the daily delivery of perishable products to monthly shipping of other items. You can also develop replenishment options for varying stock needs and their cost can increase.
4. Analyze Supplier Performance
Unreliable suppliers will cause problems in inventory planning and control. So, take appropriate action on suppliers who deliver inventory late or run out of stock regularly.
You can discuss this with your supplier to find out what the problem might be. If the problem persists, switch suppliers. Running out of stock due to unreliable suppliers shouldn’t be tolerated.
5. Invest in Inventory Management Systems
If your business is small, manually managing inventory with notepads and spreadsheets is possible. But as the business grows, more time is required to plan your inventory. The odds of running out of stock are high.
Good inventory management software will make the task easier. Before choosing software, understand your company’s needs. Technology should provide easy-to-use analytics that is relevant to your business.
For example, the Enterprise Resource Planning (ERP) system is an all-in-one software that will help you to manage inventory, sales, and accounting. This system integrates inventory management with other business processes, reducing the risk of stockouts and improving overall efficiency.
Another option is a point-of-sale (POS) system, which allows for real-time tracking of inventory levels. POS systems can also integrate with online platforms like Shopify or WooCommerce, making it easier to manage both physical and online sales.
Good management of inventory plans will ensure your business doesn’t run out of stock. You can lose customers if they fail to get the goods they need. Avoid losses emanating from poor stock planning by tracking inventory, determining sales, and firing unreliable suppliers.
How to Improve Inventory Management in Your Small Business
Generally, when we talk about improvement, there are three steps you can take right now to improve inventory management in your business.
1. Always know your inventories (track inventory data)
Inventory control is an essential practice for all businesses. Knowing your inventory is a key part of knowing what you have available to sell. Keeping track of what you have in stock means you’ll know if you need to buy more. It also means that if there’s an emergency situation, you’ll have the correct items available to meet customers’ needs.
Generally, you will need to know two types of inventories: aggregated and item-based inventory.
Aggregated inventory is inventory according to classification.
When it comes to the item-based inventory, you can easily disaggregate your aggregated inventory and come to the level of the item.
2. Analyze your inventory
Are you running low on supplies or ingredients? Are there things that have to be bought in bulk because of their expense? Do you need to source more ingredients to meet demand? Is your website lacking the visual impact you’d like? What does your business need to improve? Start with the inventory question. Ask yourself how long it will take to get new items into your inventory or how long it will take to restock your shelves. Once you have a rough timeline in mind, you can start to brainstorm solutions to those challenges.
It’s pretty easy to see when a product is selling, but that’s not always the case. When looking at your inventory, the first thing to do is find out how many customers you have and how much inventory you have. This can be done using basic tools like Google Sheets. After that, look at the conversion rate (the number of purchases divided by the number of potential customers) and the average order value per customer.
When you know what inventories exist in your company or better said, what inventories flow through your company, you can easily analyze what’s going on.
Analyze your inventories to find answers to the following questions:
- What are the needs of flow and kind of inventory in your small business?
- Which aggregated and individual inventory items are most important for your company?
- Can you see some supply and demand patterns?
- What are the costs associated with inventory?
- What functions do inventories do in your company?
- How can you control each item?
- How much to order at a given time to keep low-level inventories?
- When is the best time to make orders?
3. Implement continuous improvement related to the inventory management system
When you know the answers to the above questions, you can simply implement a continuous improvement system relayed to inventory management.
The best inventory management systems have the capability of tracking inventory in real time, automatically recognizing shortages and orders, and predicting future demand. These systems, including the perpetual inventory system, offer real-time tracking of stock levels and rely on advanced technology to streamline inventory management processes. They can also be used to determine when inventory is running low, giving the organization the ability to order more stock when needed.
You need always be sure that you have a solid foundation for operations that support both supply chain efficiency and profitability. When continuous improvement programs are properly implemented, the result is improved inventory turn, more timely delivery of products, lower costs, increased customer satisfaction, and improved operational performance.
Simply find the biggest problems and make an action plan to implement improvements.
Common Reasons Small Businesses Outsource Inventory Management
If you are a micro or small business or even a startup without financial resources for stocking facilities, technology, and processes, you can check outsourcing as an option.
Here are just a few of the many benefits you might enjoy by outsourcing your small business inventory management to a third party.
1. Faster Shipping to Customers
Shipping time frames can be problematic if you live in an outlying state or an isolated country. Customers might expect fast shipping, but you won’t always be able to provide it due to your location. However, businesses offering inventory management can sometimes solve this problem if they have a centrally-located warehouse.
For example, GovernmentProcurement.com prides itself on storage and distribution, with significant inventories of supplies, parts, and equipment housed within a 42,000-square-foot warehouse. Their central location means their clients purchasing aerospace parts from them can enjoy short shipping routes to both coasts.
2. Improve Your Process Efficiency
It’s easy for your attention to be dragged away from your core business tasks when you’re so busy focusing on your inventory. Improve your process efficiency by outsourcing inventory management to a business solely focused on inventory management.
When you outsource such a resource-intensive task, you can concentrate on advertising, marketing, and providing superior customer service.
3. Save Space and Money
Warehouse space is expensive, with the average business owner having to part with rental payments of $9.7 per square foot in the United States. This can equate to tens of thousands of dollars annually. When you outsource inventory management, you don’t require as much space and can often lease or rent much smaller premises for your daily operations.
In part, space and money savings are what make dropshipping retail operations so popular with entrepreneurs and business owners. They can work from the comfort of their own home while still having access to a significant amount of merchandise to satisfy their customers’ buying needs.
4. Lower Unit Rate Costs
When you have limited space, you might only order limited quantities of products to suit your storage facility or business. As a result, you don’t always benefit from competitive unit rates that contribute to higher profit margins and better cash flow. That can often change when you outsource inventory management. You can purchase bulk stock quantities, store them with your inventory manager, and take advantage of bulk deals.
5. Benefit from Experts
Business owners wear many hats, but you don’t have to wear them all. You might be an expert in your field, but that doesn’t mean you’re an expert in inventory management. Rather than spend countless hours getting up to speed with the intricacies of stock control and management, save yourself a great deal of stress by taking advantage of people who are already experts and can handle it for you.